

Recent analytical reports show that the absorption of industrial park land has increased again since Q2/2026. Rental demand in 2027 is forecast to continue rising, primarily driven by FDI enterprises expanding production.
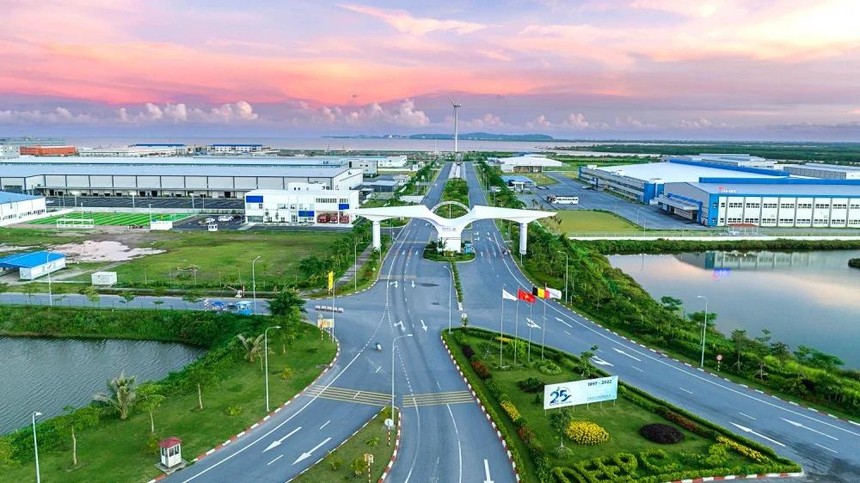
Industrial park land absorption increases again
According to SSI Research data cited by Investment Securities Newspaper and CafeF, the North absorbed approximately 217 hectares of industrial park land in Q2/2026. In Q1/2026, this figure was 134 hectares. This is the highest quarterly level since Q1/2024.
In the South, the absorbed area in Q2/2026 reached approximately 67 hectares. This figure was 57 hectares in Q1 and approximately 10 hectares in the same period last year.
The MarketBeat Q2/2026 report by Cushman & Wakefield recorded that the cumulative industrial park land bank in the North has exceeded 25,200 hectares. The average occupancy rate is 64%, 2.7 percentage points lower than the same period last year.
New supply concentrated in key industrial provinces
According to CBRE, approximately 1,347 hectares of new industrial park land are expected to enter the market from Q4/2026 to the end of 2027. Of this, the North has 664 hectares and the South has 683 hectares.
In the North, new supply is mainly located in Bac Ninh, Thai Nguyen, Hai Phong, Hung Yen, and provinces bordering Hanoi. In the South, supply is concentrated in Dong Nai, Binh Duong, Long An, Tay Ninh, and Ba Ria – Vung Tau.
Rental demand in 2027
SSI Research forecasts that the area of new lease contracts and memoranda of understanding in 2027 will reach approximately 1,000 hectares, an increase of 18.6% compared to 2026. The additional growth is expected to come mainly from tier-2 industrial parks, where FDI enterprises are relocating and expanding production. Tenants from China, Taiwan, and Hong Kong are forecast to remain the group with the highest demand.
Also according to SSI Research, a segment of tenants is cautious regarding US tax policies. This group prioritizes renting ready-built factory buildings to test the market or expand on a smaller scale.
Rental prices
According to CBRE data cited by CafeF, the rental price for industrial park land in the North is currently about 143 USD/m², an increase of 2.9% compared to the same period last year. The price in the South is about 185 USD/m², an increase of 3.7%. These prices are calculated for the entire lease term.
SSI Research forecasts that rental prices will remain flat in 2027. The reason is that new industrial parks may offer more competitive prices to attract large tenants and achieve rapid occupancy.
In the ready-built segment, JLL Vietnam recorded the asking rent for factory buildings in the key Northern market at 5.3 USD/m²/month, and warehouses at 4.5 USD/m²/month.
Infrastructure and policy
According to SSI Research, many transport routes are expected to help reduce logistics costs for industrial parks. These include the North – South Expressway, the expanded Long Thanh – Dau Giay route, the Bien Hoa – Vung Tau Expressway, along with Ring Road 3 and Ring Road 4.
Regarding policy, Resolution 10-NQ/TW dated June 8, 2026, and the amended Law on Investment aim at three contents: reducing administrative procedures, providing capital incentives for eco-industrial parks, and decentralizing authority to local levels.
Compiled sources: SSI Research and CBRE (via Investment Securities Newspaper – tinnhanhchungkhoan.vn, October 9, 2026; CafeF/Market Pulse, October 9, 2026); Cushman & Wakefield Vietnam (MarketBeat Q2/2026); JLL Vietnam.